

Self - Credit Builder & Cards

- 38.49K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on Self - Credit Builder & Cards from Appgk
I approached Self as a practical finance app rather than a general-purpose banking replacement. Its focus is narrower: helping people build credit and work toward a credit card without a credit check during the initial process. That makes it especially interesting for someone who is new to credit, rebuilding after financial trouble, or simply wants a more structured route than applying for cards and hoping for approval.
My overall impression is positive, but with an important qualification: this is a credit-building tool, not a shortcut to a strong credit profile. The value comes from consistent use, patience, and understanding what the app is designed to do. If you expect instant access to spending money, fast rewards, or a normal bank account with every everyday feature, you may find it too limited. If your main goal is to establish a more dependable credit history, its focused approach makes sense.
How Self feels in everyday use
The app is developed by Self Financial, Inc. and sits in the finance category. It is free to download, carries an Everyone age rating, and has reached more than a million installs. Those figures suggest that it is not a niche experiment, but the more useful question is whether its workflow fits your financial situation.
When I think about a typical user, I picture someone who has income but little usable credit history. Perhaps you pay rent and utilities on time, yet traditional lenders still have very little information with which to assess you. Self gives that person a more deliberate starting point than repeatedly submitting applications for conventional cards. The no-credit-check positioning is central here because it removes one of the most intimidating barriers for people who are just beginning.
Best Parts of Self - Credit Builder & Cards
Things to Keep in Mind About Self - Credit Builder & Cards
The experience is best understood as a guided commitment. You are not simply downloading a card wallet and receiving an open line of spending money. Instead, the app is built around the idea that regular, manageable payments can support credit-building progress. That distinction matters because it changes how you should judge the product. The question is not “How much can I spend today?” but “Can I follow this plan reliably over time?”
For example, imagine someone who receives a paycheck every other week and wants to start building a record before applying for a mainstream card. A sensible routine would be to review the available plan carefully, choose an obligation that comfortably fits the budget, and treat each payment as a fixed monthly priority. The app may be useful in that situation because it creates structure. It is less suitable if the person is already struggling to cover rent, food, or essential bills.
News and Features Related to Self - Credit Builder & Cards

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The most important practical rule is to choose a commitment you can maintain without stretching your budget. Credit-building products can be counterproductive when users focus on improving their score while ignoring cash flow. A missed payment or an obligation that forces you to rely on expensive borrowing defeats the purpose of the exercise.
A focused route instead of a conventional card application
Compared with a typical secured credit card, Self puts more emphasis on the building process itself. A secured card usually asks you to provide money upfront and then manage purchases and repayments within a revolving account. That can be useful for people who are ready to use a card regularly and understand statement dates, utilization, and payment timing.
Don't want to read the full review?
Self is more appealing to someone who wants a clearly separated credit-building arrangement rather than an open invitation to spend. That separation can reduce temptation. You are less likely to confuse available credit with extra income when the product is presented as a planned financial step. On the other hand, users who specifically need flexible purchasing power may prefer a secured card from a conventional issuer.
It also differs from credit-monitoring apps. A monitoring app can show scores, alerts, or report information, but watching your credit does not automatically create a repayment history. Self is aimed at taking an active role in that process. I would therefore see monitoring apps as companions rather than direct substitutes: one helps you observe, while this app is intended to help you build through a structured product.
Screenshots
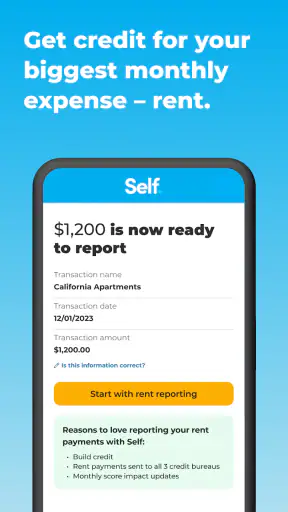
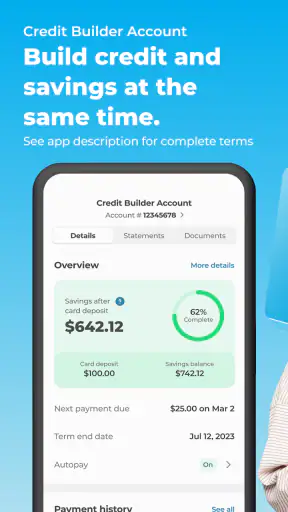
Compared with a normal debit card, the difference is even clearer. Debit spending uses money you already have and generally does not serve the same credit-building purpose. Self should not replace your checking account, emergency fund, or basic spending plan. It belongs alongside those tools, not in place of them.
What the current version tells me about the product
The current version is 10.0.0, and the app was released on March 30, 2018. I read that combination as evidence of a product that has had time to mature rather than a newly launched concept. The version number alone does not prove that every screen is perfect, but it does indicate a substantial stage in the app’s development.
For an existing user, a mature version can be reassuring because the core journey is likely to be more established than it would be in an early release. It also raises expectations. Once an app has reached this point, people reasonably expect clear explanations, dependable account information, and a smooth way to understand what action is required next.
The app’s public reception is strong, with a 4.7 average from roughly 102 thousand ratings and about 38 thousand written reviews. I would not treat popularity as proof that it will suit everyone, but it does make the product easier to take seriously. A large user base also means that the app has been tested in many different financial situations, even though your own outcome will depend on your payment behavior and broader credit profile.
What I would not do is assume that a newer version number guarantees a particular result. An update can improve navigation without changing the underlying financial terms or the time needed to build credit. The useful evidence is still your ability to understand the agreement, make payments consistently, and monitor how the arrangement fits your goals.
How existing users should approach the product
If you already use Self, the best way to benefit from it is to make the payment routine nearly automatic in your personal budget. I would place the due date beside rent, utilities, and other fixed obligations rather than treating it as an optional app task. A calendar reminder is helpful, but the stronger habit is checking your bank balance before the payment date and leaving enough room for essentials.
Another useful habit is to review the app after each payment rather than opening it only when something goes wrong. Look for the next required action, confirm that your account information is current, and keep your personal records. This does not mean obsessively checking your score every day. It means knowing where you stand and catching confusion early.
There is also a psychological advantage to separating credit-building money from spending money. If you mentally label the obligation as a long-term financial task, you are less likely to treat it like a source of disposable cash. I would avoid moving the payment amount around in your budget each month. Stability is more valuable here than trying to make the plan fit a constantly changing lifestyle.
For someone rebuilding credit after missed payments, patience is especially important. Self cannot erase an existing history simply because you begin using the app. It may provide a new pattern of responsible behavior, but that pattern has to coexist with the rest of your financial record. Paying the app on time while leaving other accounts delinquent is not a complete recovery strategy.
For someone with no credit history, the app can be easier to understand than juggling several products at once. Start with one clear objective: establish a reliable record. Do not immediately add multiple applications, store cards, or high-interest offers just because you feel encouraged by early progress. A simple plan is easier to manage and less likely to create unnecessary inquiries or debt.
Where the experience still has limits
The biggest limitation is that credit-building takes time. Self can offer a path, but it cannot make lenders approve you, guarantee a particular score, or turn a thin file into a strong one overnight. Anyone promising themselves a quick transformation is likely to be disappointed. The app is most valuable when your expectations are measured.
The second limitation is flexibility. A structured product may feel restrictive if your income changes from month to month. Someone working irregular shifts, relying on seasonal earnings, or managing frequent emergencies should examine the payment obligation very carefully before enrolling. A plan that looks affordable on a good month can become stressful when hours are reduced.
There is also a learning curve around credit itself. The app can make the process more approachable, but it does not remove the need to understand basic ideas such as payment history, existing debt, and the difference between building credit and borrowing for consumption. I would spend time reading every agreement and checking how the product fits with other accounts before committing.
Users who want rewards, travel benefits, a high spending limit, or a full set of banking services should probably compare other options first. A rewards card may be better for an established borrower who pays balances in full. A secured card may be better for someone who wants to practice using revolving credit. A conventional bank app may be better for direct deposits and everyday money management. Self’s strength is its focused purpose, and that same focus makes it unsuitable as an all-in-one financial home.
Even the free price needs to be interpreted sensibly. Free to download does not mean every financial arrangement connected with the service should be judged only by the absence of an app charge. Before starting, I would read the full terms, understand the payment schedule, and consider the total commitment. In finance, the important cost is often connected to the product structure rather than the download itself.
Three practical strategies that make more sense
First, decide what success means before opening the app. If your goal is to prepare for a future card application, write down the reason and the timeframe you have in mind. This prevents you from judging the app by daily excitement. You can then ask whether the payments remain affordable and whether your broader credit behavior is improving.
Second, pair Self with a simple monthly review. I would check income, essential bills, the Self obligation, and any other credit accounts in one sitting. This reveals a trade-off that is easy to miss: adding a credit-building payment can be sensible only when it does not reduce your ability to maintain existing accounts. The app works best as part of a complete budget, not as an isolated fix.
Third, use the product as a bridge, not a permanent excuse to avoid learning about other credit tools. Once you become more comfortable, compare the next step carefully. You may decide that continuing with a structured builder is right, or that a secured card better matches your needs. The decision should be based on spending discipline and repayment capacity, not simply on wanting a larger limit.
A less obvious but valuable approach is to avoid applying for several alternatives at the same time. People who are denied by one lender sometimes respond by submitting multiple applications in quick succession. That can create more confusion and may not help the underlying problem. A deliberate Self plan gives you a chance to build habits first, then reassess from a stronger position.
Who should use it and who should wait
I would recommend Self to adults who have a thin or damaged credit profile, want a guided starting point, and can make a predictable payment without sacrificing necessities. It is also a reasonable option for someone who feels that an ordinary credit card would encourage overspending. The focused design can make the objective easier to keep in view.
I would be more cautious if your income is unstable, you already have several overdue accounts, or you are looking for emergency cash. In those cases, a nonprofit credit counselor, a debt-management conversation, or a basic spending plan may be more urgent than opening another financial product. Self is not a replacement for help with a debt crisis.
I would also tell experienced card users to look elsewhere if their main priorities are rewards, flexible purchases, or premium benefits. The app’s purpose is not to compete with every credit card. It is aimed at a different stage of the financial journey.
What I would watch before and after signing up
Before enrolling, I would pay close attention to the complete terms, the amount and timing of each payment, and how the product fits with my existing obligations. I would not rely on the store summary alone to make a financial decision. The summary explains the broad purpose, but your decision should come from understanding the actual agreement presented during enrollment.
After enrolling, I would watch for three things: whether the payment remains comfortable, whether the account information is easy to follow, and whether my wider credit behavior is moving in the right direction. If the app becomes confusing, I would contact support through the available in-app route and keep records of important communications.
I would also watch how future updates affect the experience. Version 10.0.0 shows a product that has evolved considerably since its original release, but evolution should be judged by practical improvements: clearer explanations, fewer points of friction, and better visibility into what users need to do. I would welcome changes that make the financial commitment easier to understand without suggesting that software alone can speed up credit history.
My final view is that Self is a credible, focused option for building credit when you approach it with discipline. Its free app access, no-credit-check starting point, and structured purpose make it more approachable than many conventional applications for people with limited history. At the same time, it demands patience and careful budgeting. Use it as a controlled step toward healthier credit habits, not as a promise of instant approval or extra spending power.
For the right user, that honesty is the product’s real strength. It gives a beginner a clearer route than guessing which card might accept them. For the wrong user, the same structure can feel restrictive or add pressure to an already tight budget. I would choose Self when the goal is steady credit-building progress, and I would choose a different financial tool when the goal is everyday banking, rewards, emergency borrowing, or flexible card spending.
Self - Credit Builder & Cards FAQ
What is Self - Credit Builder & Cards, and how does it work?
Self is a financial app designed to help users build or establish credit through a Credit Builder Account and related card products. Instead of receiving the loan money upfront, you generally make scheduled payments into an account while Self reports eligible payment activity to major credit bureaus. After completing the account terms, the accumulated funds, minus applicable fees and interest, may be returned to you. Approval, reporting, and product availability depend on eligibility and location.
Does Self - Credit Builder & Cards guarantee that my credit score will increase?
No. Self cannot guarantee a specific credit-score improvement. Consistently making payments on time may help create a positive payment history, but your score is also affected by factors such as existing debts, credit utilization, account age, credit inquiries, and information reported by other lenders. Late or missed payments may negatively affect your credit. Before signing up, review the agreement carefully and confirm which products report to which credit bureaus.
What fees, interest, and other costs should I expect?
Self products can involve an administrative or account-opening fee, interest charges, and other costs depending on the Credit Builder Account or card selected. The total amount you pay may therefore be higher than the funds ultimately released to you. Card products may also have annual, maintenance, late-payment, or other applicable fees. Costs and terms can change, so check the current disclosures, APR, payment schedule, and fee table in the app before accepting an offer.
Can I use a Self card like a regular credit card, and how is it different?
Self offers card options whose availability and structure may differ from a traditional unsecured credit card. Depending on the product, your spending limit may be connected to funds in a secured account, and you may need to make payments according to the card agreement. The card can potentially help with credit-building when used responsibly, but it is not free money. Confirm whether the card is secured, its limit, interest rate, fees, and reporting policy before using it.
Is Self - Credit Builder & Cards safe, and what should I check before downloading?
Self is a financial service, so users should download the app only from the official Google Play Store or Apple App Store and verify the developer name. The app may request sensitive information for identity verification, account management, and credit-related services. Use a strong password, enable available security features, and avoid sharing login codes. Most importantly, read the privacy policy and account agreement, understand automatic-payment requirements, and contact official support if you notice suspicious activity.











